Why traditional risk models fall short
Classical actuarial models lean heavily on historical loss data and a small set of rating variables. They work well when the world looks like the past — and poorly when it does not. Cyber, climate, and supply-chain risks have all out-paced the data carriers have on file.
What AI adds
Modern models bring three new capabilities to underwriting:
- High-dimensional features — satellite imagery for property risk, telematics for auto, transaction graphs for financial lines.
- Continuous re-pricing — risk scores updated every time new data lands, instead of once per renewal.
- Explainable outputs — SHAP values and counterfactuals so underwriters can defend a decision under audit.
Operational pitfalls
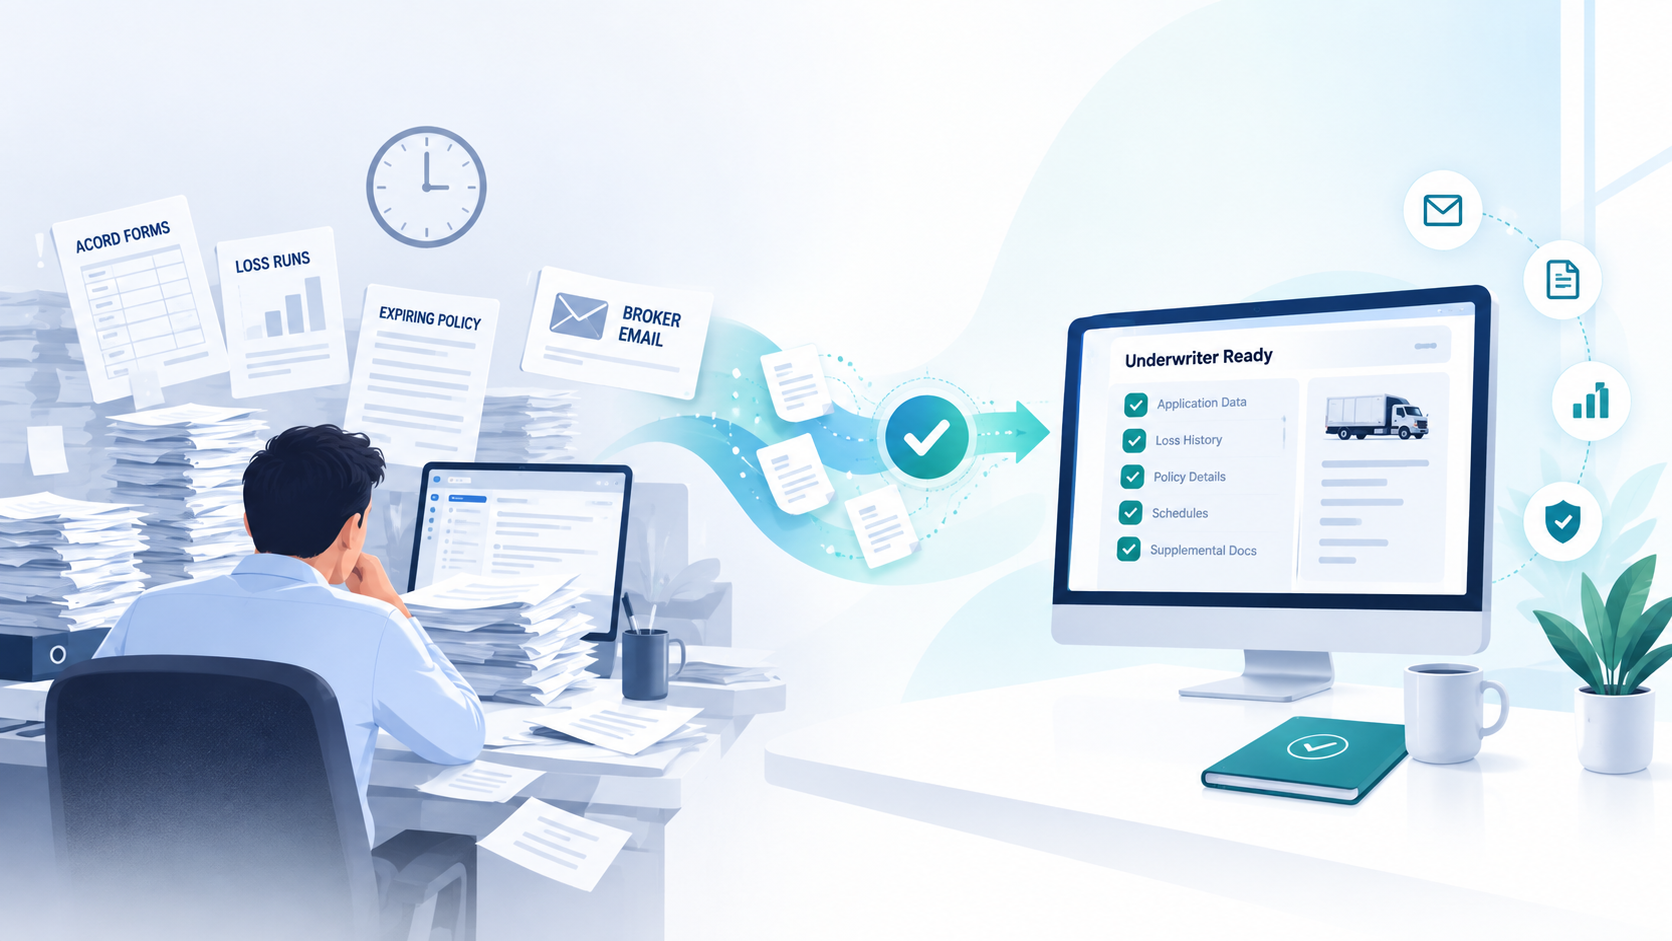
Adopting ML scoring without changing the underwriting workflow is the single most common failure mode. The model produces a number; nobody trusts it; the desk goes back to spreadsheets. Fix this by integrating scores directly into the underwriting workbench, with clear thresholds for autonomous bind, refer-to-senior, and decline.
Closing thought
Risk assessment is moving from periodic to continuous. Carriers that build that muscle now will price more accurately and lose less to adverse selection.